
Albania taxes employment income at 13% and 23%. It taxes self-employed business income up to a substantial threshold at nothing at all, and has committed to that until the end of 2029.
Albania overhauled its personal income tax in 2024, introducing a progressive structure for employment income and an unusually generous treatment for the self-employed. The two sit side by side and produce very different outcomes for people doing similar work.
Employment income is taxed at 13% on annual income up to ALL 2,040,000 and 23% above, with an exempt band at the bottom of the monthly scale that phases out as income rises.
Business income of self-employed individuals and commercial entrepreneurs is taxed at 0% up to ALL 14 million a year — roughly EUR 120,000 — with 23% applying above that. The zero rate is legislated to run to 31 December 2029.

Every condition for the 0% regime, and the date it ends.
Your residency status is the first step
Albania applies the principle of worldwide taxation. Resident individuals are taxed on all sources of income in and outside Albania; non-residents only on income generated within Albanian territory.
That matters for the 0% regime. It is a rate applying to a category of income, not a territorial exemption, so the question of what falls inside the Albanian base is separate from the question of what rate applies to it.
Maintain accurate records of:
• Days present in Albania in each tax year;
• Whether your income is employment income or business income;
• Annual business income against the ALL 14 million threshold;
• Whether your clients are resident or non-resident;
• Whether any client has a permanent establishment in Albania; and
• Any other country that may also treat you as resident.
The tax rates
Income | Albanian treatment |
Employment income up to ALL 2,040,000 | 13% |
Employment income above ALL 2,040,000 | 23% |
Lower monthly bands | An exempt amount that phases out as income rises |
Business income up to ALL 14 million | 0%, to 31 December 2029 |
Business income above ALL 14 million | 23% |
Dividends | 8% |
Investment income | Taxed under its own category |
Scope for residents | Worldwide income |
👨💻 The 0% is the standout feature and it is time-limited. A freelancer earning the equivalent of EUR 68,000 through self-employment pays no Albanian income tax on it at all under the current law, but the regime carries an explicit end date and should be modelled as expiring rather than as permanent.
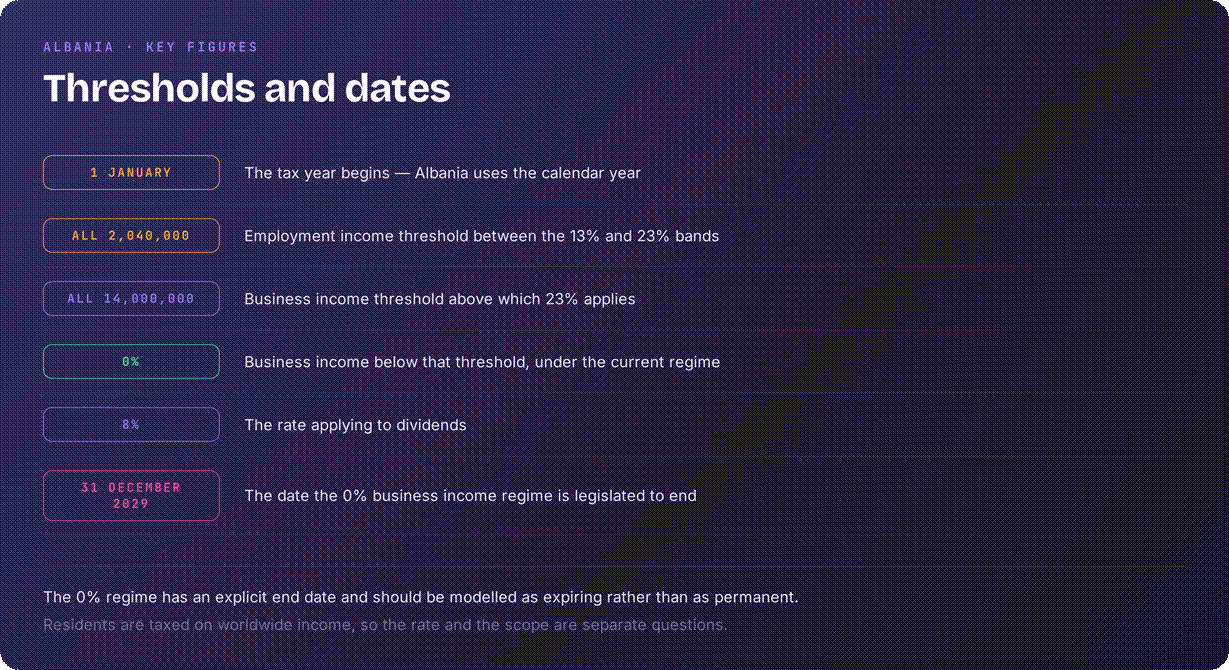
The dates and thresholds that govern the position.
The non-resident client carve-out
The 2024 reform introduced criteria designed to identify self-employed people who are, in substance, employees of a single client; the same problem Serbia addresses with its independence test.
Those criteria expressly do not apply to self-employed individuals serving exclusively non-resident individuals or non-resident entities without a permanent establishment in Albania.
The effect is that a freelancer working solely for foreign clients sits outside the recharacterisation rules that would catch someone servicing a single Albanian company. For the remote-working population, that is the provision that makes the 0% regime usable rather than theoretical.
What the reform also brought
The overhaul extended the list of non-taxable income considerably — private health insurance, employer contributions to private pension plans, life and accident insurance, work-related equipment, meal benefits and various other employer-provided perks. Travel allowances and accommodation reimbursements also remain outside employment income taxation.
For an employee those exclusions can be worth a meaningful amount, and they are frequently overlooked in comparisons that look only at the headline bands.
Case study: Arta and Besart, same income
Arta is employed by an Albanian company on ALL 3,000,000 a year. The first ALL 2,040,000 is taxed at 13% and the balance at 23%, giving an effective rate of around 16%.
Besart earns the same ALL 3,000,000 as a self-employed consultant serving clients in Germany and Italy. His business income is below the ALL 14 million threshold, so his Albanian income tax is nil, and the recharacterisation criteria do not reach him because his clients are non-resident.
Two people, the same income, in the same city. The difference is entirely structural, and it runs until the end of 2029 unless the law changes first.
Filing and the compliance calendar
The Albanian tax year follows the calendar year, administered by the General Directorate of Taxation. Employment income is withheld through payroll, and self-employed individuals register and file under the rules applying to their category.
Prepare in good time:
• Registration with the tax administration and a NIPT number;
• Records of business income against the ALL 14 million threshold;
• Documentation of client residence and permanent establishment status;
• Evidence supporting any non-taxable income claimed;
• Records of foreign income, since residents are taxed worldwide; and
• Evidence of foreign tax paid.
Model the sunset, not just the rate
Consider:
• Whether your income is employment income or business income;
• How close your business income runs to ALL 14 million;
• Whether all your clients are genuinely non-resident;
• That the 0% is legislated only to 31 December 2029;
• That residents are taxed on worldwide income regardless of the rate;
• Which employer-provided benefits fall outside employment income; and
• Whether your former country accepts that you have left.
Your Albania checklist
1. Establish whether your income is employment income or business income;
2. Track annual business income against the ALL 14 million threshold;
3. Confirm that all clients are genuinely non-resident;
4. Confirm those clients have no permanent establishment in Albania;
5. Model the position from 2030, when the 0% is due to end;
6. Remember residents are taxed on worldwide income regardless;
7. Identify employer-provided benefits that fall outside taxable income;
8. Register with the tax administration before invoicing;
9. Keep documentation of client residence status; and
10. Confirm your former country accepts that you have left.
Frequently asked questions
What are the Albanian income tax rates?
13% on employment income up to ALL 2,040,000 a year and 23% above, with an exempt amount at the lower end of the monthly scale that phases out as income rises.
Is self-employment income really taxed at 0%?
Business income of self-employed individuals and commercial entrepreneurs up to ALL 14 million a year — roughly EUR 120,000 — is taxed at 0% under the current law, with 23% applying above that threshold.
How long does the 0% last?
It is legislated to 31 December 2029. That is an explicit end date, so any plan built around it should model what happens from 2030 rather than assuming continuation.
Does the 0% mean my foreign income is untaxed?
No. Albania taxes residents on worldwide income, so the 0% is a rate applying to a category of income rather than a territorial exemption. Scope and rate are separate questions.
What is the non-resident client carve-out?
Criteria introduced to identify disguised employment expressly do not apply to self-employed individuals serving exclusively non-resident individuals or non-resident entities without a permanent establishment in Albania.
Why does that carve-out matter?
Because it means a freelancer working solely for foreign clients sits outside the recharacterisation rules that would catch someone servicing a single Albanian company. For remote workers it is what makes the regime usable.
How are dividends taxed?
At 8%, which is low by regional standards and sits separately from both the employment bands and the business income regime.
What income is non-taxable?
The reform extended the list considerably — private health insurance, employer contributions to private pension plans, life and accident insurance, work equipment, meal benefits and similar perks, along with travel allowances and accommodation reimbursements.
Official sources and further reading
• General Directorate of Taxation, Albania
Important information
This article is general information and does not constitute tax, legal, immigration or financial advice, and does not create a client relationship. Tax outcomes depend on travel history, income sources, treaty status and the law applying to the relevant year. Rates, thresholds and regimes change, and some measures described may be proposed rather than enacted; this article reflects our understanding as at the date of publication. Obtain advice from a suitably qualified professional before acting or refraining from action.
