
Iceland taxes employment income heavily and capital income lightly. Between the two sits a relief that exempts a quarter of a qualifying specialist’s salary for three years, and it has to be applied for within three months.
Iceland taxes residents on worldwide income and non-residents on Icelandic-source income. Employment income runs through three progressive brackets combining state and municipal tax, with a top combined rate of roughly 46%, and the thresholds are adjusted annually.
Capital income is treated very differently. Dividends, interest and capital gains are taxed at a flat 22% — less than half the top rate on employment income — which makes the characterisation of income unusually consequential here.
Sitting between them is the foreign expert relief. A qualifying specialist who relocates to Iceland for work pays income tax on only 75% of their salary for the first three years of employment, both for withholding and final assessment.
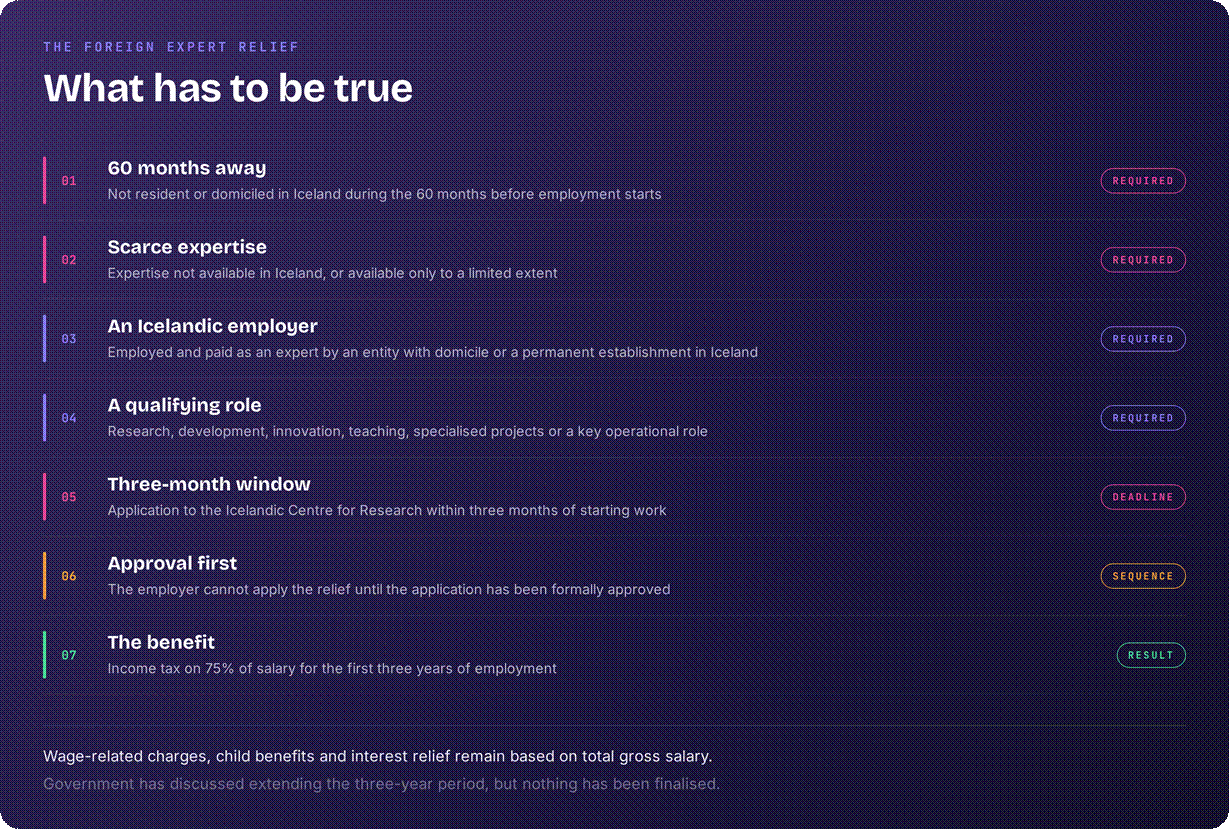
Every condition must hold, and the window is short.
Your residency status is the first step
You are Icelandic tax resident broadly by being present in Iceland for 183 days or more in a twelve-month period. Residents are taxed on worldwide income; non-residents only on income sourced in Iceland.
Non-resident remuneration in the form of payments to directors and committee members, grants, or fees for independent personal services and artistic performances is taxed by assessment at 20% plus the average municipal rate, rather than through the ordinary brackets.
Maintain accurate records of:
• Days present in Iceland across twelve-month periods;
• The date employment in Iceland commenced, for the three-month application window;
• The 60 months preceding that date, for the prior non-residence condition;
• Income separated between employment and capital;
• Pension contributions, which are deductible up to a limit; and
• Any other country that may also treat you as resident.
The tax rates
Item | Position |
Employment income | Three progressive brackets, state plus municipal |
Top combined rate | Roughly 46%, with thresholds adjusted annually |
Municipal component | Varies by municipality within a published range |
Capital income | 22% flat on dividends, interest and gains |
Foreign experts | Income tax on 75% of salary for three years |
Non-resident specified income | 20% plus the average municipal rate |
Personal tax credit | Deducted from calculated tax, transferable between spouses |
Pension contributions | Deductible up to 4% of total employment income |
The personal tax credit reduces the tax rather than the base, and an unused credit can be transferred between spouses or registered partners. For a household with one earner that transfer is worth more than it appears at first glance.
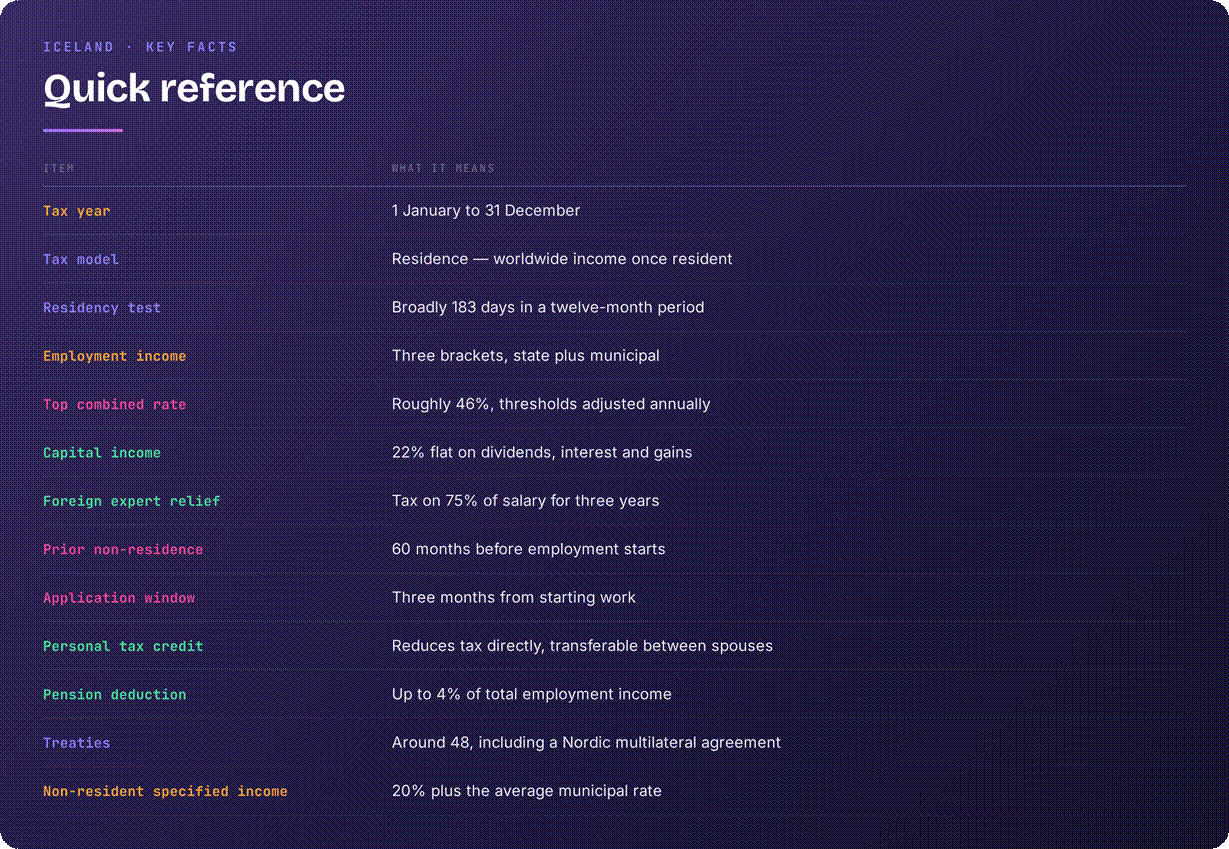
The Icelandic position at a glance.
The foreign expert relief in detail
An employee qualifies as a foreign expert where all of the following hold:
• They have not been resident or domiciled in Iceland during the 60 months before the start of employment, with the first three months of stay in Iceland not counted;
• They possess expertise not available in Iceland, or available only to a limited extent;
• They are employed by a legal entity with domicile or a permanent establishment in Iceland, and paid as an expert by that entity; and
• They work in research, development or innovation, in teaching, on specialised projects, or perform project management, construction management or another key role essential to the company’s operations.
Both the specialist and the employer can submit the application, through the Icelandic Centre for Research. A committee appointed by the Ministry of Finance and Economic Affairs assesses whether the conditions are met.
Once approved, the expert pays income tax on 75% of income for the first three years. Wage-related charges, child benefits and interest relief are still based on total gross salary, so the relief reduces income tax specifically rather than every calculation that touches your pay.
There has been active discussion within government about extending the length of the relief, supported by growing Icelandic industries, though nothing has been finalised.
What makes Iceland attractive
Against a high headline rate on employment income, several features work in the opposite direction:
• Capital income at a flat 22%, which is low for Western Europe and less than half the top employment rate;
• The foreign expert relief, exempting a quarter of salary for three years for qualifying specialists;
• A personal tax credit that reduces tax directly and is transferable between spouses;
• Pension contributions deductible up to 4% of total employment income;
• A treaty network covering around 48 countries, including a multilateral Nordic agreement; and
• An administratively straightforward system, with employment income handled through withholding.
The honest qualification is that Iceland is a high-tax country for ordinary employment income, and the expert relief reaches a narrow group. For a researcher, engineer or specialist recruited into a qualifying role it is genuinely valuable; for a general commercial hire it does not apply.
Case study: Anders misses the window
Anders is recruited from Denmark to a Reykjavík biotech company as a research scientist. He has not lived in Iceland for a decade, his expertise is specialised, and his role is squarely within research and development.
He qualifies on every condition. What he does not do is apply within three months of starting work, because nobody told him the deadline existed and his employer cannot apply the relief until approval comes through.
The relief is worth a quarter of his salary being exempt for three years. The application takes a form and a committee decision, and the window for it closes long before his first tax return is due.
Filing and the compliance calendar
The Icelandic tax year follows the calendar year. Employment income is withheld at source, and individuals file an annual return with the tax authority, with joint filing available to married and cohabiting couples who meet the conditions.
Prepare in good time:
• An Icelandic identification number and filing access;
• The foreign expert application, within three months of starting work;
• Evidence of 60 months of prior non-residence;
• Documentation of the specialised nature of the role;
• Records of capital income for the 22% treatment; and
• Pension contribution records against the 4% limit.
Apply early, and characterise correctly
Consider:
• Whether your role falls within the qualifying categories for the relief;
• Whether you satisfy the 60-month prior non-residence condition;
• That the application window is three months from starting work;
• That the employer cannot apply the relief before approval;
• How much of your income is capital income at 22% rather than employment income;
• That the relief reduces income tax, not every wage-related calculation; and
• Whether a treaty covers your home country, given a network of around 48.
Your Iceland checklist
1. Check whether your role falls within the qualifying categories;
2. Confirm 60 months of prior non-residence before employment starts;
3. Diarise the three-month application window from your first working day;
4. Apply through the Icelandic Centre for Research, with your employer;
5. Do not expect the employer to apply the relief before approval;
6. Separate capital income, taxed at 22%, from employment income;
7. Claim the personal tax credit and transfer any unused portion;
8. Track pension contributions against the 4% deduction limit;
9. Check whether a treaty covers your home country; and
10. Note that wage-related charges still follow total gross salary.
Frequently asked questions
What is the foreign expert relief?
A relief under which a qualifying specialist pays income tax on only 75% of their salary for the first three years of employment in Iceland, applying to both withholding and final assessment.
Who qualifies?
Someone not resident or domiciled in Iceland during the 60 months before employment starts, possessing expertise not available in Iceland, employed by an Icelandic entity, and working in research, development, innovation, teaching, specialised projects or a key operational role.
How do I apply?
Through the Icelandic Centre for Research, by either the specialist or the employer, within three months of starting work. A committee appointed by the Ministry of Finance assesses whether the conditions are met.
What happens if I miss the deadline?
The relief is lost for that employment. The employer cannot apply it before approval, and the window closes long before the first tax return is due, so it needs handling at the point of starting work.
How is capital income taxed?
At a flat 22% on dividends, interest and capital gains — less than half the top rate on employment income, which makes the characterisation of income unusually consequential.
What are the employment tax rates?
Three progressive brackets combining state and municipal tax, with a top combined rate of roughly 46%. Thresholds are adjusted annually and the municipal component varies within a published range.
Does the relief reduce everything?
No. It reduces income tax specifically. Wage-related charges, child benefits and interest relief continue to be based on total gross salary, so the benefit is narrower than a straight 25% pay increase.
Is the three-year period being extended?
There has been active discussion within government about extending it, supported by growing Icelandic industries, but nothing has been finalised. Plan on three years unless and until that changes.
Official sources and further reading
• Skatturinn — Iceland Revenue and Customs
Important information
This article is general information and does not constitute tax, legal, immigration or financial advice, and does not create a client relationship. Tax outcomes depend on travel history, income sources, treaty status and the law applying to the relevant year. Rates, thresholds and regimes change, and some measures described may be proposed rather than enacted; this article reflects our understanding as at the date of publication. Obtain advice from a suitably qualified professional before acting or refraining from action.
