
If you are considering Ireland, several questions need answering before you move or rearrange your finances: where will you be tax resident, will Ireland tax your worldwide income, can foreign income and gains stay outside the Irish charge, what happens when you transfer offshore funds to Ireland, and how will your Irish obligations interact with tax elsewhere?
Ireland is often described as a high-tax country because the top rate of income tax is 40%. That headline does not tell the whole story for someone who is Irish tax resident but not Irish domiciled.
🔎 What the remittance basis does. Qualifying foreign income and gains may remain outside the Irish charge while they stay offshore. Once those funds are brought into Ireland, Irish tax may apply. It changes the point at which foreign income becomes taxable — it does not make it permanently tax-free.
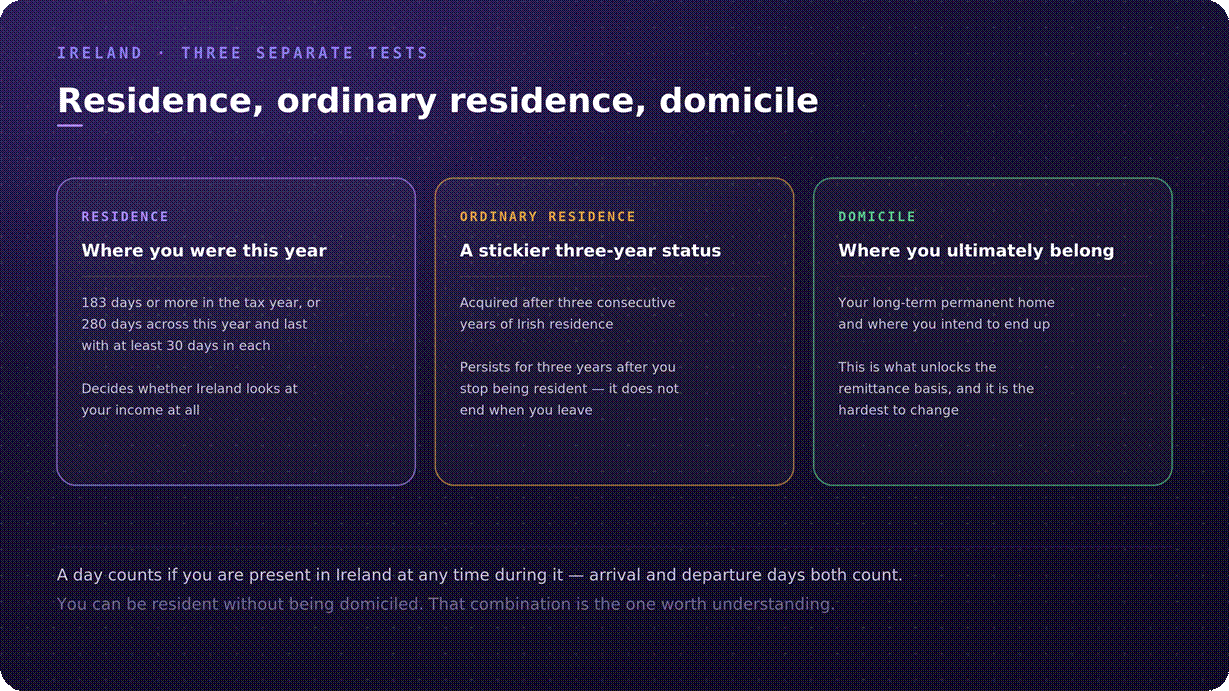
Three separate concepts, each answering a different question.
First, are you tax resident?
Ireland’s tax year is the calendar year, and there are two day-count tests:
• The single-year test — you are present in Ireland for 183 days or more during the tax year; or
• The two-year test — you are present for 280 days or more across the current and immediately preceding tax years, with at least 30 days in each.
⏱️ How days are counted. You are treated as present for a day if you are in Ireland at any time during that day, so arrival and departure days both count as full days. This is stricter than a midnight-based test, and it is a common source of miscounting.
Case study: Sarah's travel pattern
Sarah spends 170 days in Ireland in one year and 115 days the year before. She believes she is non-resident because she has not exceeded the single-year threshold.
Her combined presence is 285 days across the two years, with more than 30 days in each — so she may meet the two-year test. This is the trap for people who split their time across borders and only ever check the current year.
Retain flight records, accommodation records, work calendars and travel documents. If you travel regularly, keep a contemporaneous day-count schedule rather than reconstructing one later.
Then, ordinary residence and domicile
Residence is not the only status that matters, and the other two are frequently overlooked.
Ordinary residence is acquired once you have been Irish tax resident for three consecutive years. It then persists for three years after you stop being resident, which means leaving Ireland does not immediately end your exposure.
Domicile is a different concept again: your long-term permanent home and where you ultimately intend to belong. You may become Irish tax resident without acquiring an Irish domicile — for example, moving for employment while keeping a permanent home, family base and long-term intention elsewhere.
Your domicile of origin generally continues unless you establish a new one through clear evidence of both an intention to live permanently in Ireland and no intention to return to your domicile of origin. The assessment is fact-specific: nationality, family connections, property, business interests, immigration status and long-term intentions all bear on it.
Do not assume either way. Holding an Irish residence permission, renting an Irish home or working for an Irish company does not automatically make you Irish-domiciled. Equally, describing yourself as temporary does not settle the question.
What the remittance basis covers
For a qualifying non-domiciled individual who is Irish tax resident, Ireland generally taxes Irish-source income and gains, and qualifying foreign income and gains to the extent they are remitted to Ireland.
Income | When Ireland taxes it |
Irish employment income | Always, whether or not you move the money |
Irish business profits | Always |
Irish rental income | Always |
Foreign dividends and interest | When remitted to Ireland |
Foreign rental income | When remitted to Ireland |
Gains on non-Irish assets | When proceeds or value are remitted |
Duties performed in Ireland | Under the employment rules, wherever paid |
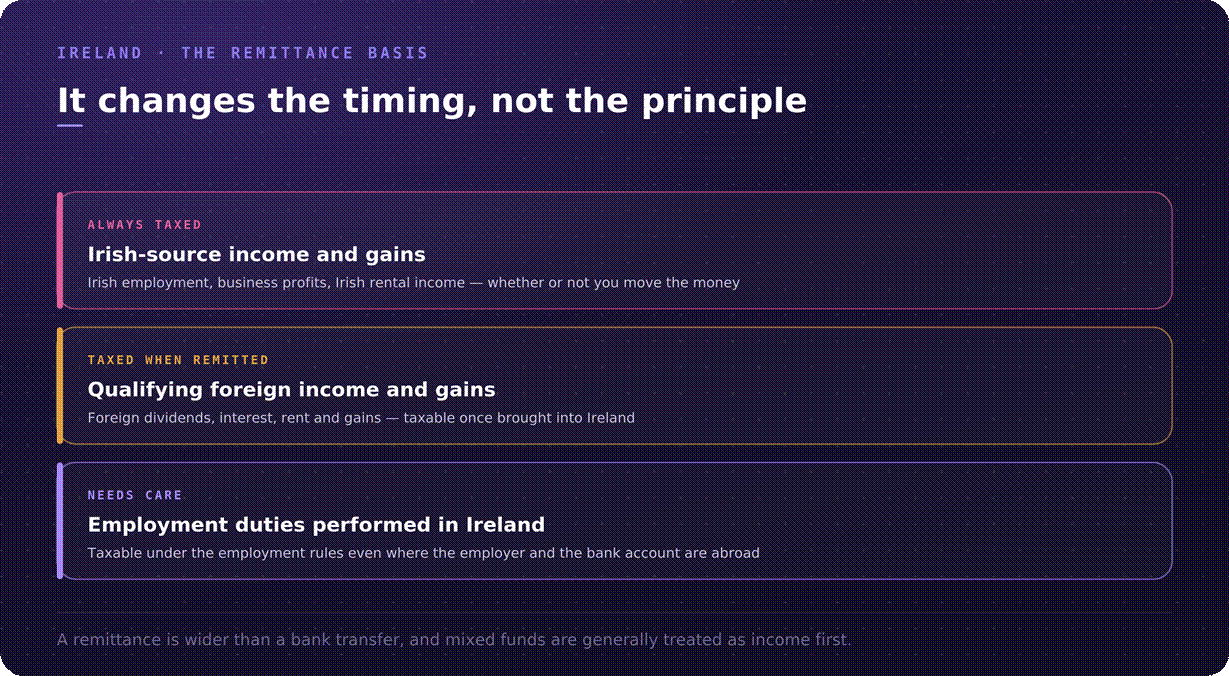
What is always taxed, what is taxed on remittance, and what needs care.
Foreign employment income needs particular care. Income relating to duties physically performed in Ireland is generally dealt with under the employment income rules rather than protected because it is paid offshore. An overseas employer and a foreign bank account do not, by themselves, keep it outside the Irish charge.
The 40% top rate is also only part of the picture. Your effective liability depends on the rate bands, tax credits and the Universal Social Charge, which sits alongside income tax rather than within it.
Treat remittances as a planning decision
A remittance is wider than a direct transfer to an Irish bank account. Depending on circumstances it can include using foreign funds to pay Irish expenses, transferring value to Ireland, or using offshore money in a way that benefits you in Ireland.
Case study: Mark's offshore account
Mark is Irish tax resident and non-domiciled. He receives foreign investment income into an overseas brokerage account and leaves it there, then transfers part of it to his Irish bank account to pay rent and household expenses.
The amount transferred may be treated as a remittance and become relevant for Irish tax. That the money originally arose abroad does not prevent an Irish charge once it is brought in.
Mixed funds are the real difficulty. Where an account holds both capital and accumulated income, withdrawals are not automatically treated as capital — remittances from mixed funds are generally treated as coming from income first. Keeping clean, separate accounts from the outset is far easier than untangling one later.
In practice, that means keeping clear records for capital, income and gains; separating pre-arrival funds from post-arrival income; avoiding unnecessary transfers between offshore and Irish accounts; documenting the source of every substantial transfer; and taking advice before remitting investment proceeds or accumulated savings.
If you are also taxed elsewhere
Some countries tax their citizens on worldwide income regardless of where they live. Where that applies to you, the Irish remittance basis does not remove those obligations, and you may still need to consider annual filing, foreign account reporting, foreign tax credits, withholding taxes and the relevant treaty.
Ireland has 76 double taxation agreements, which can coordinate taxing rights and relieve double taxation. A treaty does not remove filing obligations, and the relief available depends on the type and source of income. If you receive salary, consulting income, rent, dividends or gains from more than one country, coordinate advice on both sides before deciding where to hold or remit funds.
Compliance
The tax year is the calendar year. Self-assessed taxpayers file a Form 11, with the pay-and-file deadline of 31 October following the end of the tax year. An extension to mid-November is generally available where both the return is filed and the payment made online, so check the date published for your year.
Preliminary tax may also be payable during the year. Begin preparing well before the deadline, particularly if you need to reconstruct travel days, trace historical account balances, or calculate the portion of employment income connected with Irish workdays.
Ireland also operates a separate domicile levy aimed at certain Irish-domiciled individuals, which is filed and paid on a self-assessment basis by 31 October following the valuation date. It is worth being aware of even if it does not apply to you.
Your checklist
1. Track your Irish presence throughout each calendar year;
2. Check both the single-year and two-year residency tests;
3. Consider whether you have become ordinarily resident, and when that would lapse;
4. Document your domicile and long-term intentions;
5. Separate Irish-source from foreign-source income;
6. Identify where your employment duties are physically performed;
7. Keep foreign income and gains clearly traceable, and avoid mixed accounts;
8. Review whether a proposed transfer could be a remittance;
9. Coordinate foreign tax credit planning across both countries; and
10. Prepare for the 31 October pay-and-file deadline in good time.
Frequently asked questions
How many days make me Irish tax resident?
183 days or more in the tax year, or 280 days or more across the current and previous year with at least 30 days in each. A day counts if you are in Ireland at any time during it, so both travel days count.
What is ordinary residence, and why does it matter?
It is acquired after three consecutive years of Irish residence and persists for three years after you stop being resident. It means leaving Ireland does not immediately end your Irish exposure, which surprises people who plan only around the day count.
Does the remittance basis make my foreign income tax-free?
No. It changes when foreign income and gains become taxable, not whether. While the funds stay offshore they may sit outside the charge; bring them into Ireland and Irish tax may apply.
What counts as a remittance?
More than a bank transfer. Using foreign funds to pay Irish expenses, transferring value into Ireland, or using offshore money in a way that benefits you in Ireland can all count, depending on the circumstances.
What happens with a mixed account?
Remittances from funds containing both capital and accumulated income are generally treated as coming from income first. Separating accounts before you arrive is far simpler than trying to trace sources afterwards.
My employer is abroad and pays me abroad. Am I safe?
Not where the duties are performed in Ireland. That income is generally dealt with under the employment rules regardless of where the employer sits or which account the salary lands in.
Is 40% really the top rate?
It is the top rate of income tax, but the Universal Social Charge and PRSI apply alongside it, so your effective position on employment income is higher than 40%.
When do I file?
31 October following the end of the calendar year for self-assessed taxpayers, generally extended to mid-November where you both file and pay online. Preliminary tax may also be due during the year.
Official sources and further reading
• Revenue guidance on tax residence
• Revenue guidance on domicile and the domicile levy
• Citizens information on tax residence and domicile in Ireland
Important information
This article is general information and does not constitute tax, legal, immigration or financial advice, and does not create a client relationship. Tax outcomes depend on travel history, income sources, treaty status and the law applying to the relevant year. Rates, thresholds and regimes change, and some measures described may be proposed rather than enacted; this article reflects our understanding as at the date of publication. Obtain advice from a suitably qualified professional before acting or refraining from action.
