
Laos taxes independent contractors on gross revenue rather than profit, at 3% for services. Capital gains are charged at 2%. Both are far lower than the employment scale suggests.
The headline for Laos is a personal income tax scale reaching 25%, and on that basis it usually gets written off. The figure that matters for anyone self-employed is a different one entirely.
Sole traders and independent contractors are subject to profit tax on gross revenue, not on profit, at rates of 1% for agriculture, industry and other production, 2% for commerce, and 3% for services.
For a consultant or freelancer that 3% of gross is the operative number. It is charged without computing deductible expenses, which removes both the tax and the administration in one step.
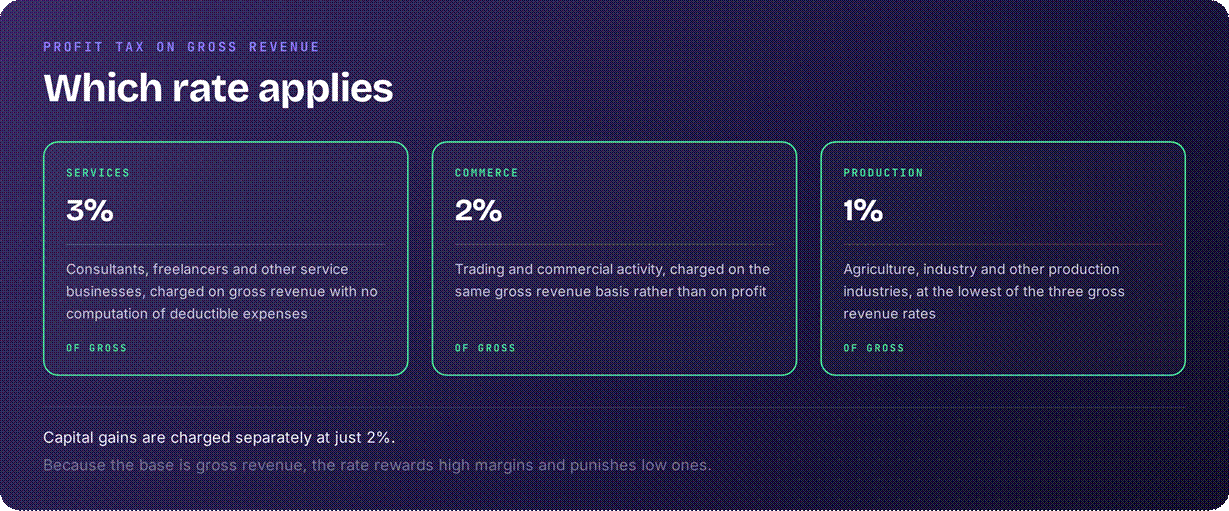
Three rates, and the activity decides which.
Your residency status is the first step
The rule is stated unusually plainly. Expatriates who work in Lao PDR and obtain remuneration in Lao PDR are obligated to pay personal income tax regardless of the period of their employment and stay. There is no threshold for Lao-source pay.
Separately, foreigners who stay in Lao PDR for a period or periods aggregating more than 183 days in any one-year period and obtain remuneration from a foreign country are obligated to pay personal income tax on that foreign remuneration.
So the 183-day test governs foreign pay, not local pay. Someone on a short assignment paid locally is taxable from day one; someone paid from abroad is outside the charge until the count passes 183 days.
Maintain accurate records of:
• Days present across rolling one-year periods;
• Whether remuneration is paid in Laos or from a foreign country;
• Gross revenue by activity type, for the profit tax rate;
• Whether you are an employee or an independent contractor;
• Disposal proceeds and dates, for the 2% gains charge; and
• Any other country that may also treat you as resident.
The tax rates
Item | Rate |
Employment income up to LAK 1,300,000 | 0% |
LAK 1,300,001 to 5,000,000 | 5% |
LAK 5,000,001 to 15,000,000 | 10% |
LAK 15,000,001 to 25,000,000 | 15% |
LAK 25,000,001 to 65,000,000 | 20% |
Above LAK 65,000,000 | 25% |
Profit tax on gross revenue, services | 3% |
Capital gains tax | 2% |
The profit tax is charged on gross revenue rather than profit, which cuts both ways. A service business with high margins pays 3% of turnover and keeps the rest; one with thin margins pays 3% of turnover whatever the profit was.
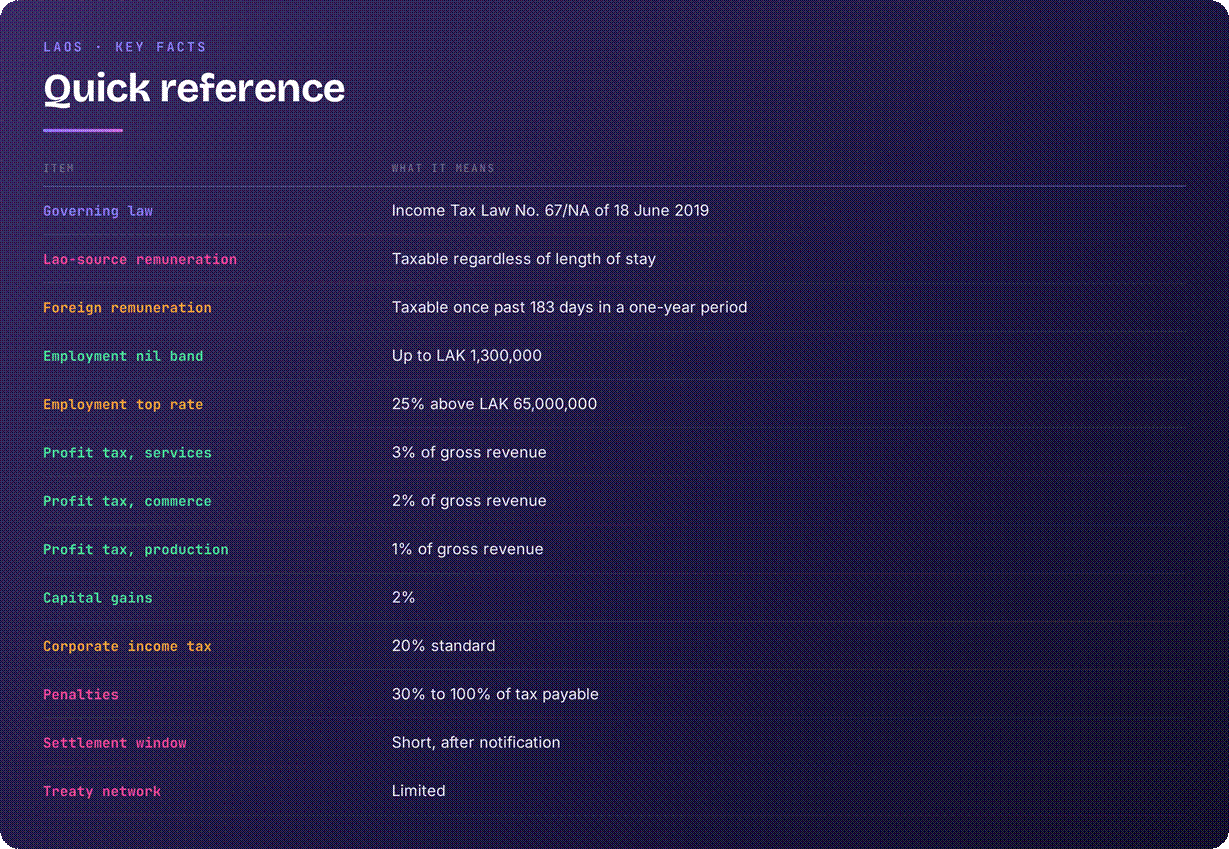
The Lao position at a glance.
What makes Laos attractive
For an independent contractor the numbers are genuinely competitive:
• 3% of gross revenue for a service business, with no expense computation required;
• 2% for commerce and 1% for agriculture, industry and production;
• Capital gains at just 2%, among the lowest rates anywhere;
• A nil band on employment income up to LAK 1,300,000;
• Foreign remuneration outside the charge until 183 days have accumulated;
• A simple six-band employment scale with no phase-outs; and
• A low cost of living.
The honest qualifications are that Lao-source remuneration is taxable from the first day with no threshold for a short stay, that gross-revenue taxation punishes a low-margin model, and that the treaty network and banking infrastructure are both limited.
Case study: Sitha invoices from Vientiane
Sitha runs a design consultancy from Vientiane with revenue equivalent to USD 80,000 and costs of USD 20,000. As an independent contractor providing services, her profit tax is 3% of gross revenue — around USD 2,400.
Under a conventional profit-based system at, say, 20%, she would pay tax on USD 60,000 of profit — USD 12,000. The gross-revenue basis is markedly better for her.
Reverse the margins and it reverses too. A reseller with USD 80,000 of revenue and USD 72,000 of costs pays the same 3% of gross — USD 2,400 on USD 8,000 of profit, an effective rate of 30%.
Filing and the compliance calendar
The system runs under Income Tax Law No. 67/NA of 18 June 2019. Employment income is withheld, and independent contractors account for profit tax on gross revenue. Penalties for unpaid tax range from 30% to 100% of the amount payable, with a short window to settle after notification.
Prepare in good time:
• Registration with the tax authorities;
• Gross revenue records by activity classification;
• Evidence of whether remuneration is Lao-source or foreign;
• Day-count records across one-year periods;
• Disposal records for the 2% gains charge; and
• Prompt attention to any notification, given the short settlement window.
Margin decides whether this works
Consider:
• Your gross margin, since the profit tax is on revenue not profit;
• Which activity classification applies — 1%, 2% or 3%;
• That Lao-source remuneration is taxable from day one;
• That foreign remuneration needs 183 days before it is caught;
• That capital gains are only 2%;
• Whether you are an employee or an independent contractor; and
• The limited treaty and banking infrastructure alongside the rate.
Your Laos checklist
1. Calculate your gross margin before relying on the 3%;
2. Identify the correct activity classification for your rate;
3. Note that Lao-source pay is taxable from day one;
4. Count days for foreign remuneration against 183;
5. Track the one-year period, which is rolling;
6. Establish whether you are an employee or a contractor;
7. Keep gross revenue records rather than profit records;
8. Note that capital gains are charged at 2%;
9. Respond promptly to any notification, given short windows; and
10. Allow for a limited treaty network in your planning.
Frequently asked questions
What do independent contractors pay in Laos?
Profit tax on gross revenue rather than on profit — 1% for agriculture, industry and other production, 2% for commerce, and 3% for services. No computation of deductible expenses is required.
What is the capital gains rate?
2%, which is among the lowest anywhere. There is no separate schedule to work through beyond that.
When does foreign income become taxable?
Foreigners who stay in Lao PDR for periods aggregating more than 183 days in any one-year period and obtain remuneration from a foreign country are obligated to pay personal income tax on it. Below that, foreign remuneration is outside the charge.
What about pay from a Lao source?
Taxable from the first day. Expatriates who work in Lao PDR and obtain remuneration there are obligated to pay personal income tax regardless of the period of their employment and stay — there is no short-stay threshold.
What are the employment rates?
Nil up to LAK 1,300,000, then 5% to LAK 5,000,000, 10% to LAK 15,000,000, 15% to LAK 25,000,000, 20% to LAK 65,000,000 and 25% above that.
When does the gross-revenue basis work against you?
When margins are thin. A service business paying 3% of gross on a 10% margin faces an effective rate of 30% on profit, while one on a 75% margin faces 4%. Margin, not size, decides whether the regime helps.
What law governs the system?
Income Tax Law No. 67/NA, dated 18 June 2019, which specifies that taxation applies on a worldwide basis for entities incorporated under Lao law.
What are the penalties like?
Significant. Penalties range from 30% to 100% of the tax payable, with a short period to settle after notification and escalating consequences including account charges and suspension of business for continued non-payment.
Official sources and further reading
Important information
This article is general information and does not constitute tax, legal, immigration or financial advice, and does not create a client relationship. Tax outcomes depend on travel history, income sources, treaty status and the law applying to the relevant year. Rates, thresholds and regimes change, and some measures described may be proposed rather than enacted; this article reflects our understanding as at the date of publication. Obtain advice from a suitably qualified professional before acting or refraining from action.
