
Moldova charges a flat 12% on personal income. For anyone inside its IT Park, a single 7% of turnover replaces income tax, contributions and several other taxes outright.
Moldova’s ordinary position is simple: a flat 12% personal income tax with no brackets, and a 12% corporate income tax on profit, with 0% on reinvested profits under a small-business scheme in force through 2026.
What makes the country interesting is the Moldova Innovation Technology Park, created by Law 77/2016. A resident of the park pays a single 7% tax on sales revenue which replaces corporate income tax, employee personal income tax, employer and employee social and medical contributions, local taxes, the real estate tax and the road tax.
The park is virtual. It is not a physical location — a qualifying IT company registered anywhere in Moldova can become a resident, which removes the relocation requirement that usually accompanies a special economic zone.
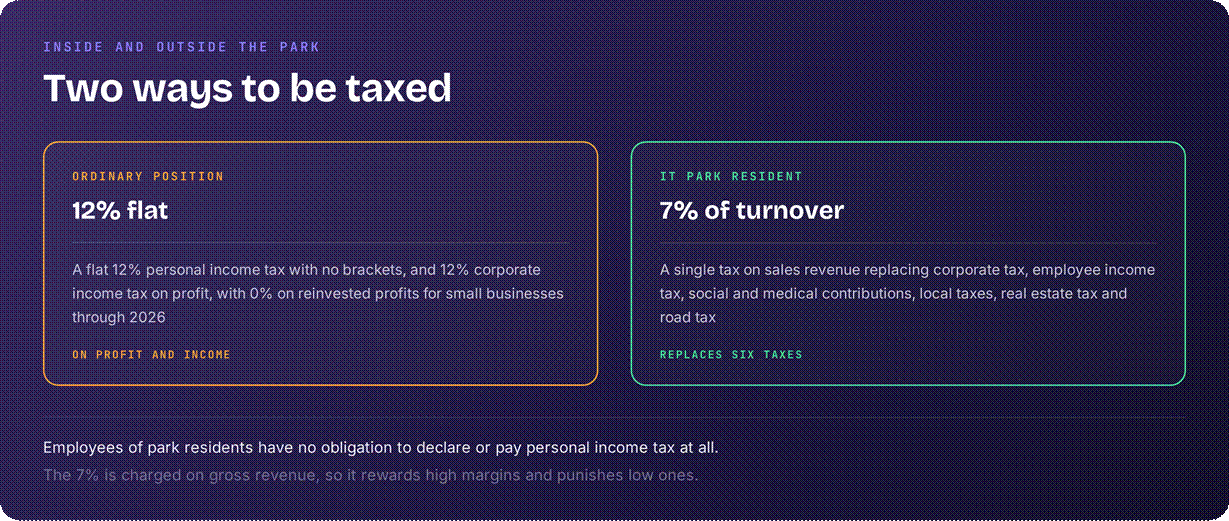
Two regimes, and margin decides which one works.
Your residency status is the first step
Moldova taxes resident individuals on their income and non-residents on Moldovan-source income. Residence broadly follows from having a permanent home in Moldova or from a substantial period of presence in the country during the fiscal year.
The residence position is worth confirming directly with the State Tax Service for your own circumstances, because the IT Park mechanism can make it less decisive than it would otherwise be: where the single 7% has been paid by the employer, the employee has no separate personal income tax obligation regardless.
Maintain accurate records of:
• Days present in Moldova during the fiscal year;
• Whether you maintain a permanent home in the country;
• Whether your employer is an IT Park resident;
• Income by source, Moldovan and foreign;
• For a company, the proportion of revenue from qualifying IT activities; and
• Any other country that may also treat you as resident.
The tax rates
Item | Position |
Personal income tax | 12% flat, no brackets |
Corporate income tax | 12% on profit |
Reinvested profits, small business scheme | 0%, in force through 2026 |
IT Park single tax | 7% of turnover |
What the 7% replaces | Corporate tax, employee income tax, contributions, local taxes, real estate tax, road tax |
Per-employee floor | Roughly MDL 5,220 a month for 2026 |
Eligibility threshold | At least 70% of revenue from listed IT activities |
Statutory guarantee | To 31 December 2035, operational to 2037 |
The per-employee floor is the constraint that decides whether the regime works. The single tax cannot fall below roughly MDL 5,220 per employee per month for 2026. For a well-paid team on strong revenue the 7% of turnover is the binding figure; for a large team on modest revenue, the floor dominates.
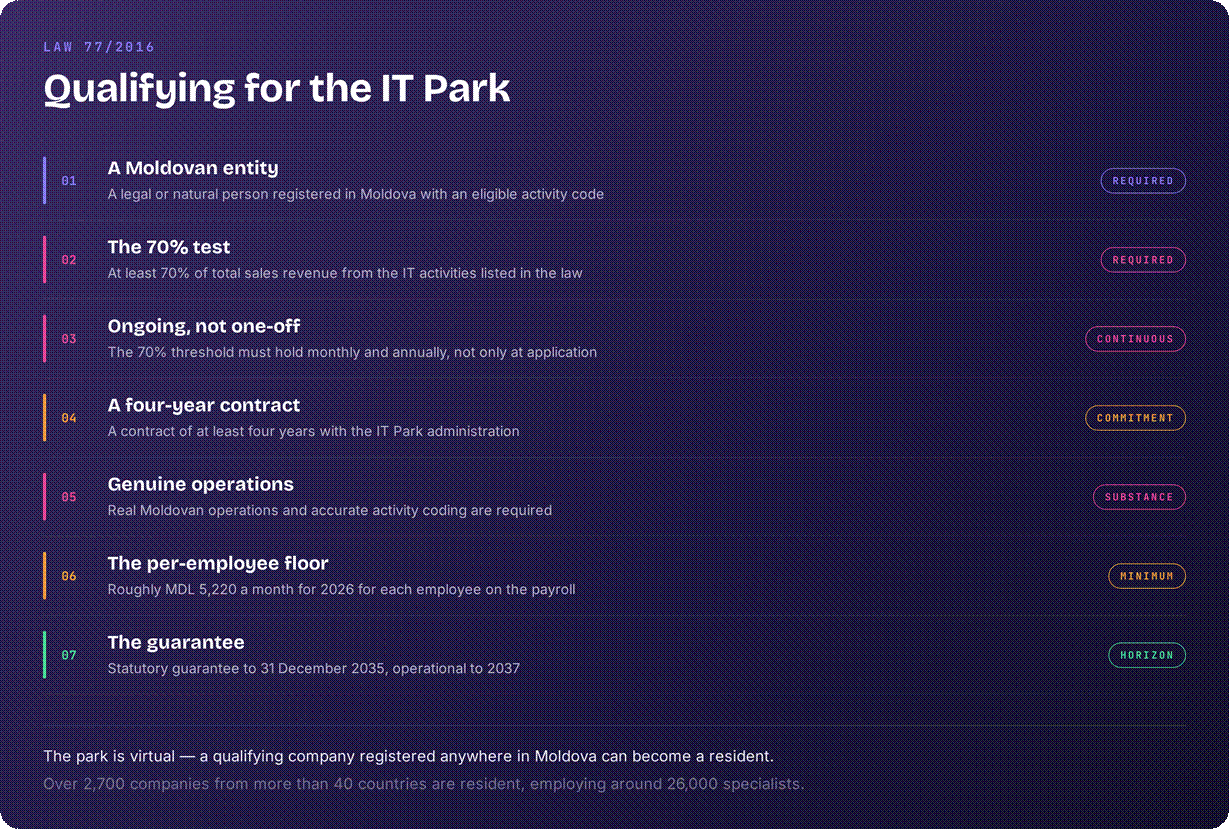
Every condition for the IT Park, and the floor beneath it.
The IT Park in detail
To qualify, a legal or natural person registered in Moldova must generate 70% or more of total sales revenue from one or more listed IT activities, and conclude a contract of at least four years with the park administration.
The listed activities are specific: computer programming, publishing of computer games, other software publishing, computer facilities management, data processing and hosting, web portals, computer consultancy, and other information technology and computer service activities.
The regime has worked. More than 2,700 companies from over 40 countries are resident, employing around 26,000 IT specialists, with combined turnover passing USD 1 billion in 2025 — up roughly a quarter on the year before. Residents span software development, outsourcing, gaming and artificial intelligence.
It is guaranteed in statute through 31 December 2035, with an operational term to 2037, which gives a planning horizon most incentive regimes do not offer.
What makes Moldova attractive
For a software or IT-services business the case is one of the strongest in Europe:
• A 12% flat personal rate outside the park, with no brackets and no phase-outs;
• A single 7% of turnover inside it, replacing six separate taxes and contributions;
• No personal income tax obligation at all for employees of park residents, who still receive social and health protection;
• The park is virtual, so no physical relocation of the business is required;
• State-guaranteed to 2035, giving a planning horizon most regimes lack;
• 0% on reinvested profits for small businesses outside the park, through 2026; and
• SEPA membership since October 2025 and EU candidate status, with salary costs well below EU levels.
The honest constraints are real. The 7% is charged on gross revenue rather than profit, so a low-margin trading or pass-through model can pay more than it would under an ordinary profit-based system. The 70% test must hold monthly and annually, not just at application. And genuine Moldovan operations and accurate activity coding are required — this is not a paper arrangement.
Case study: two businesses, one regime
Ana runs a SaaS business with revenue of EUR 900,000 and costs of EUR 300,000. Inside the IT Park she pays 7% of revenue — around EUR 63,000 — replacing corporate tax, her team’s income tax and all contributions. Under an ordinary profit-based system at 12% she would pay tax on EUR 600,000 of profit, plus payroll taxes on top.
Victor runs an IT reselling operation with the same EUR 900,000 of revenue but only EUR 60,000 of margin. His 7% is still around EUR 63,000 — more than his entire profit. The regime does not work for him at all.
The variable is margin, not size. A turnover tax rewards high-margin work and punishes low-margin work, and that single fact determines whether the headline 7% is an opportunity or a trap.
Filing and the compliance calendar
IT Park residents file a single monthly return to the State Tax Service in place of the ordinary taxes, with the 7% accrued and payable monthly on sales revenue. The 70% eligibility test must be satisfied on an ongoing basis rather than only at the point of application.
Outside the park, the ordinary flat 12% applies and the standard filing cycle follows. Prepare in good time:
• Company formation with an eligible activity code, if applying to the park;
• Confirmation that qualifying activities will generate at least 70% of revenue;
• The resident application to the IT Park administration;
• A four-year contract with the park management;
• Monthly revenue records and the single-tax return; and
• Headcount records, for the per-employee floor.
Model the margin, not the rate
Consider:
• Your gross margin, since the 7% is charged on revenue rather than profit;
• The per-employee floor against your headcount and revenue;
• Whether qualifying activities genuinely generate 70% of your revenue;
• That the 70% test must hold monthly, not just at application;
• Whether the four-year park contract suits your horizon;
• That employees of park residents have no separate income tax obligation; and
• That the regime is guaranteed to 2035, unusually far out.
Your Moldova checklist
1. Calculate your gross margin before considering the 7%;
2. Test the per-employee floor against your headcount;
3. Confirm qualifying activities generate at least 70% of revenue;
4. Check that the 70% test will hold monthly, not just at application;
5. Ensure the activity codes on the company are correct;
6. Plan for a four-year contract with the park administration;
7. Note that employees of residents have no separate income tax filing;
8. Confirm your own residence position with the State Tax Service;
9. Set up monthly single-tax reporting; and
10. Note the statutory guarantee runs to 2035.
Frequently asked questions
What is the Moldovan income tax rate?
A flat 12% on personal income with no brackets, and 12% corporate income tax on profit. A small-business scheme gives 0% on reinvested profits, in force through 2026.
What is the IT Park?
The Moldova Innovation Technology Park, created by Law 77/2016. It is a virtual park rather than a physical location, and a resident pays a single 7% tax on sales revenue replacing six separate taxes and contributions.
What does the 7% replace?
Corporate income tax, employee personal income tax, employer and employee social and medical contributions, local taxes, the real estate tax and the road tax. It is paid as a single monthly charge.
Do employees still have to file?
No. Employees of an IT Park resident have no obligation to declare and pay personal income tax to the Moldovan authorities, while still being entitled to social security and health insurance protection.
Who qualifies?
Any legal or natural person registered in Moldova generating 70% or more of total sales revenue from the IT activities listed in the law, on conclusion of a contract of at least four years with the park administration.
What is the catch?
The 7% is charged on gross revenue rather than profit. For a high-margin software exporter that is excellent; for a low-margin trading or pass-through model it can exceed the entire profit. There is also a per-employee floor of roughly MDL 5,220 a month for 2026.
How long is the regime guaranteed?
The regime is guaranteed in statute through 31 December 2035, with an operational term to 2037 — a considerably longer horizon than most incentive regimes offer.
Do I need to move the business to Moldova?
The park is virtual, so no physical relocation into a designated zone is required — a qualifying company registered anywhere in Moldova can be a resident. Genuine Moldovan operations and accurate activity coding are still required.
Official sources and further reading
Important information
This article is general information and does not constitute tax, legal, immigration or financial advice, and does not create a client relationship. Tax outcomes depend on travel history, income sources, treaty status and the law applying to the relevant year. Rates, thresholds and regimes change, and some measures described may be proposed rather than enacted; this article reflects our understanding as at the date of publication. Obtain advice from a suitably qualified professional before acting or refraining from action.
